Beyond the 2008 Supercycle? 80 Naval Mines, Sky-High Valuations, and Why Shipping Giants are Playing "Cash is King"
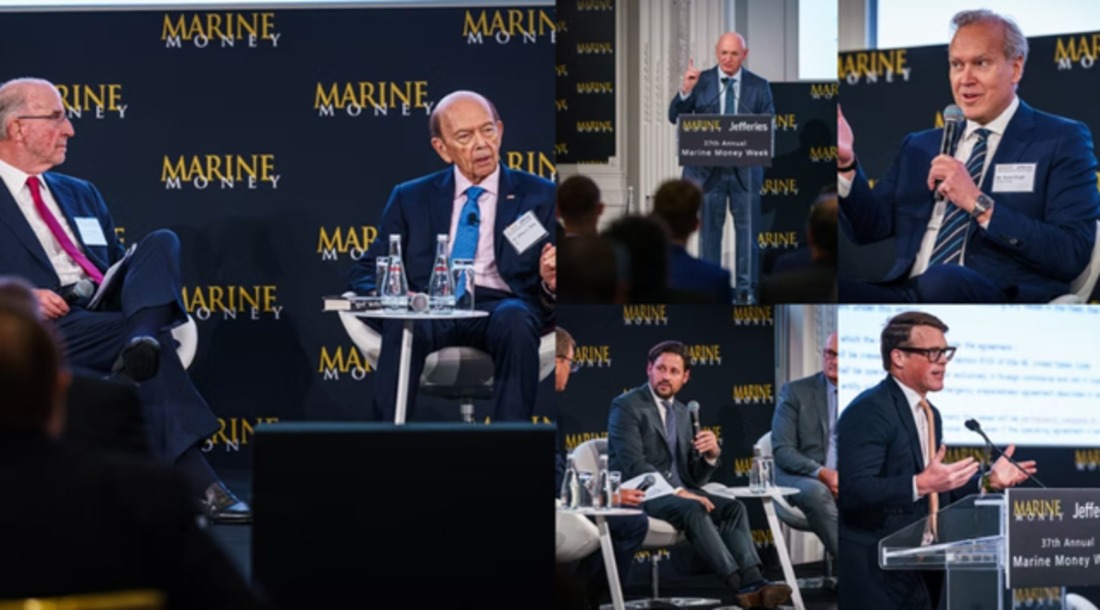
Just catching up on the core consensus from Marine Money Week (June 2026, NY), and the message is loud and clear: The global shipping market has entered a new era. Driven by geopolitical disruptions and supply chain restructuring, we are navigating an upcycle that rivals the 2003-2008 "Supercycle"—but with fundamentally different DNA.
Here are the 4 key takeaways every maritime and logistics professional needs to know:
1. The Shift to a Multipolar World The era of hyper-lean, frictionless global supply chains is over. As Jacob Shapiro (The Bespoke Group) pointed out, we are transitioning to a multipolar world. The new rule of the game? Your trade routes and partners are now heavily dictated by bilateral government relations. Or, as Omar Nokta (Clarksons) bluntly put it: "Shipping is living geopolitics day in and day out."
2. The Strait of Hormuz Chokepoint Despite recent MoUs to reopen the strait, physical realities are grim. Intertanko reports around 80 naval mines remaining in the main channel. Reopening won't be a flip of a switch. Market experts agree that "true commercial openness" will take weeks, if not months, relying on physical security, normalized insurance costs, and rebuilt market confidence.
3. 2026 vs. 2008: A Completely Different Beast Yes, valuations are touching 2008 peaks, but the supply side is entirely different. Today’s orderbook is only about 20% of the existing fleet (compared to a staggering 50% in 2008), and we are dealing with a rapidly aging global fleet. Furthermore, the industry's financial resilience is unprecedented. Five years of massive cash flows have made shipping companies practically bulletproof against upcoming downcycles.
4. High Asset Prices & "Cash is King" With VLCC newbuild prices soaring to $130 million, asset pricing has seen an irreversible structural upward shift. Are shipowners rushing into M&A? Absolutely not. Leaders from Hafnia, DHT, and Scorpio Tankers share a unified strategy: Wait and earn interest. At these peak valuations, debt-funded acquisitions simply don't make sense. The smart money is sitting in cash, waiting for the geopolitical dust to settle.
The Bottom Line: The winners of the next cycle won't be those waiting for the old globalization to return. They will be the ones who maintain financial prudence amidst sky-high asset prices and seize strategic integration opportunities during periods of disruption.
READ MORE
 Finance
HEIDMAR - Scaling for Growth: Capitalizing on Favorable Market
 Finance
Shipping’s Risk Equation Is Being Repriced as Finance, Insurance and Contracts Adapt
 Finance
Shandong Shipping and OSM Thome Form Singapore JV
 Finance
Shipowners Have Made a Fortune. How Will They Spend It?
 Finance
From RMB 1.87 Billion to RMB 4.55 Billion: What Changed at COSCO Shipping Energy in One Year?
 Finance
Net Profit Jumps 42% as NJTC Reshapes Its Liquid-Bulk Shipping Network
 Finance
Capital Is Available, but Ship Finance Is Repricing the Risk of Buying the Wrong Vessel
 Finance
Plenty of Capital, Yet Ships Still Struggle for Financing: The Structural Mismatch Reshaping Ship Finance
 Finance
COSCO SHIPPING Specialized Posts $202 Million H1 Profit as Second-Quarter Earnings Double
 Finance