GCC takes car carrier orderbook to 22 with Changhong deal
Two LNG dual-fuel ships due in 2030 extend MSC’s investment in car carrier tonnage, with all 22 newbuildings placed at Chinese yards.
MSC-owned Global Car Carriers (GCC) has added two 8,600-car-equivalent-unit (CEU) pure car and truck carriers at Changhong International Shipyard in Zhoushan, taking its newbuilding programme to 22 vessels.
Listed provisionally as Viking NB 21 and Viking NB 22, the LNG dual-fuel ships are scheduled for delivery in 2030. The contract price has not been disclosed.
The Oslo-based owner’s programme now comprises eighteen 8,600-CEU ships and four 7,000-CEU vessels, with combined nominal capacity of 182,800 CEU. Deliveries run from 2028 to 2030.
The expansion increases MSC’s exposure to the car carrier charter market. Its commercial success will depend on operators’ appetite for modern tonnage when the ships arrive, as well as the terms on which GCC secures their employment.
An expanding tonnage provider
GCC supplies ships to global and regional vehicle-shipping operators. It earns charter revenue, while its customers organise transport services and cargo bookings. The newbuildings therefore expand MSC’s shipowning portfolio; their eventual deployment will depend on charter arrangements.
The business was previously known as Gram Car Carriers. On 24 July 2024, MSC’s wholly owned subsidiary SAS Shipping Agencies Services Sàrl completed its cash offer, securing approximately 97.81% of the shares and voting rights. Gram owned 17 vessels at the time.
The company was subsequently taken private and announced its change of name to Global Car Carriers on 21 May 2026.
By late September, the newbuilding programme had reached 20 ships, with a reported value exceeding $2 billion, according to TradeWinds. That figure covered the programme at that stage, rather than the latest Changhong pair.
Reports differ on the earlier ordering sequence: Splash described eight additions to an existing 12-ship programme, while TradeWinds reported a further ten following an initial ten. Both put the September total at 20; GCC’s current fleet list confirms 22. splash247.com
Chinese yards secure the full programme
GCC’s fleet list, reviewed on 20 October 2026, allocates the ships across five Chinese building locations:
| Shipyard or building location | 8,600 CEU | 7,000 CEU | Total |
|---|---|---|---|
| China Merchants Yizheng | 6 | 0 | 6 |
| China Merchants Weihai | 6 | 2 | 8 |
| Guangzhou Shipyard International (GSI) | 2 | 2 | 4 |
| Mawei | 2 | 0 | 2 |
| Changhong International | 2 | 0 | 2 |
| Total | 18 | 4 | 22 |
Source: GCC. CEU measures nominal vehicle capacity; actual loads vary with vehicle dimensions and cargo mix.
Changhong already has an established relationship with MSC. On 18 June 2026, the yard announced steel cutting for the first of its 21,700-TEU LNG dual-fuel containerships for the group, following cooperation on 11,500-, 10,300- and 19,000-TEU designs.
The PCTC order extends that relationship into another vessel segment. For Changhong, it also adds requirements specific to vehicle carriers, including multiple cargo decks, internal traffic flows and ramp arrangements.
China’s position in this market is supported by substantial delivery experience. Höegh Autoliners’ 2025 annual report, citing Hesnes fleet data, says Chinese yards built 62 of the 76 deep-sea PCTCs delivered that year, or about 81%.
Using several yards can give GCC access to more building slots and help spread deliveries. It also increases the work involved in coordinating specifications, construction supervision and equipment supply.
Demand growth meets a delivery wave
GCC is committing capital during a period of growth in both vehicle shipments and vessel supply.
Höegh Autoliners estimated that global deep-sea light-vehicle shipments increased by 10% in 2025, with Chinese exports a major driver. Its annual report put the global deep-sea PCTC fleet at 773 ships and 4.9 million CEU at the end of that year, with another 139 vessels on firm order.
The charter market strengthened further in 2026. In results released on 20 August, Höegh said the July charter price index was 60% above its first-quarter level, supported by rising Chinese exports of vehicles and high-and-heavy cargo.
These figures illustrate why fleet growth alone does not determine market conditions. Longer voyages, port delays and empty repositioning can absorb additional capacity. Faster turnaround or shorter routes can release it.
For ships arriving in 2028–2030, the critical variables will be demand at delivery, competing newbuilding capacity and changes in automotive production. More overseas manufacturing by carmakers could alter the routes and distances over which finished vehicles move.
Fuel choice and cargo flexibility
Design particulars from Shanghai Merchant Ship Design & Research Institute (SDARI), linked from GCC’s website for its 8,600-CEU class, specify five liftable decks and a stern-quarter ramp rated at 200 tonnes. Shore power, a battery system and ammonia-ready provisions are also listed.
Adjustable deck heights and heavy-duty ramps broaden the cargo mix to include trucks and some construction equipment. Larger ships can lower transport costs per vehicle, provided operators maintain sufficient utilisation and match the vessels to port infrastructure.
Propulsion arrangements have been disclosed for part of the programme. Everllence announced on 15 June 2026 that four GCC 8,600-CEU vessels at China Merchants Jinling Shipyard would receive 6S60ME-GI Mk10.7 engines, manufactured by CSSC Engine Co., Ltd. in Qingdao. That announcement concerns the Jinling quartet, not the latest Changhong pair.
LNG dual-fuel propulsion provides fuel flexibility, but its climate performance depends on engine technology, methane leakage and fuel production. IMO’s lifecycle framework assesses emissions from production through onboard consumption, covering carbon dioxide, methane and nitrous oxide. Fuel choice therefore remains a long-term commercial and regulatory consideration.
Charter cover will determine returns
Stronger freight markets do not automatically produce better operating margins. In its September trading update, published on 9 October 2026, Höegh Autoliners described demand as robust but said higher fuel costs and costs associated with its Middle East service continued to affect earnings. Increased fuel-surcharge compensation partly explained higher third-quarter gross freight rates.
For GCC, the key questions are how much employment is secured before delivery, whether charter income covers the cost of owning the vessels, and how competitive they remain when initial contracts expire. Charter terms for the two Changhong newbuildings have not been disclosed.
GCC’s schedule calls for four deliveries in 2028, followed by nine in each of 2029 and 2030.
That influx could give Chinese and international operators more options to charter modern vessels. For vehicle exporters, the practical benefits will depend on where those ships are deployed and whether they translate into dependable space, reliable schedules and competitive transport costs.
As deliveries approach, charter coverage and financing terms will provide a clearer measure of the expansion’s earning potential than the size of the orderbook alone.
READ MORE
 Car Carriers
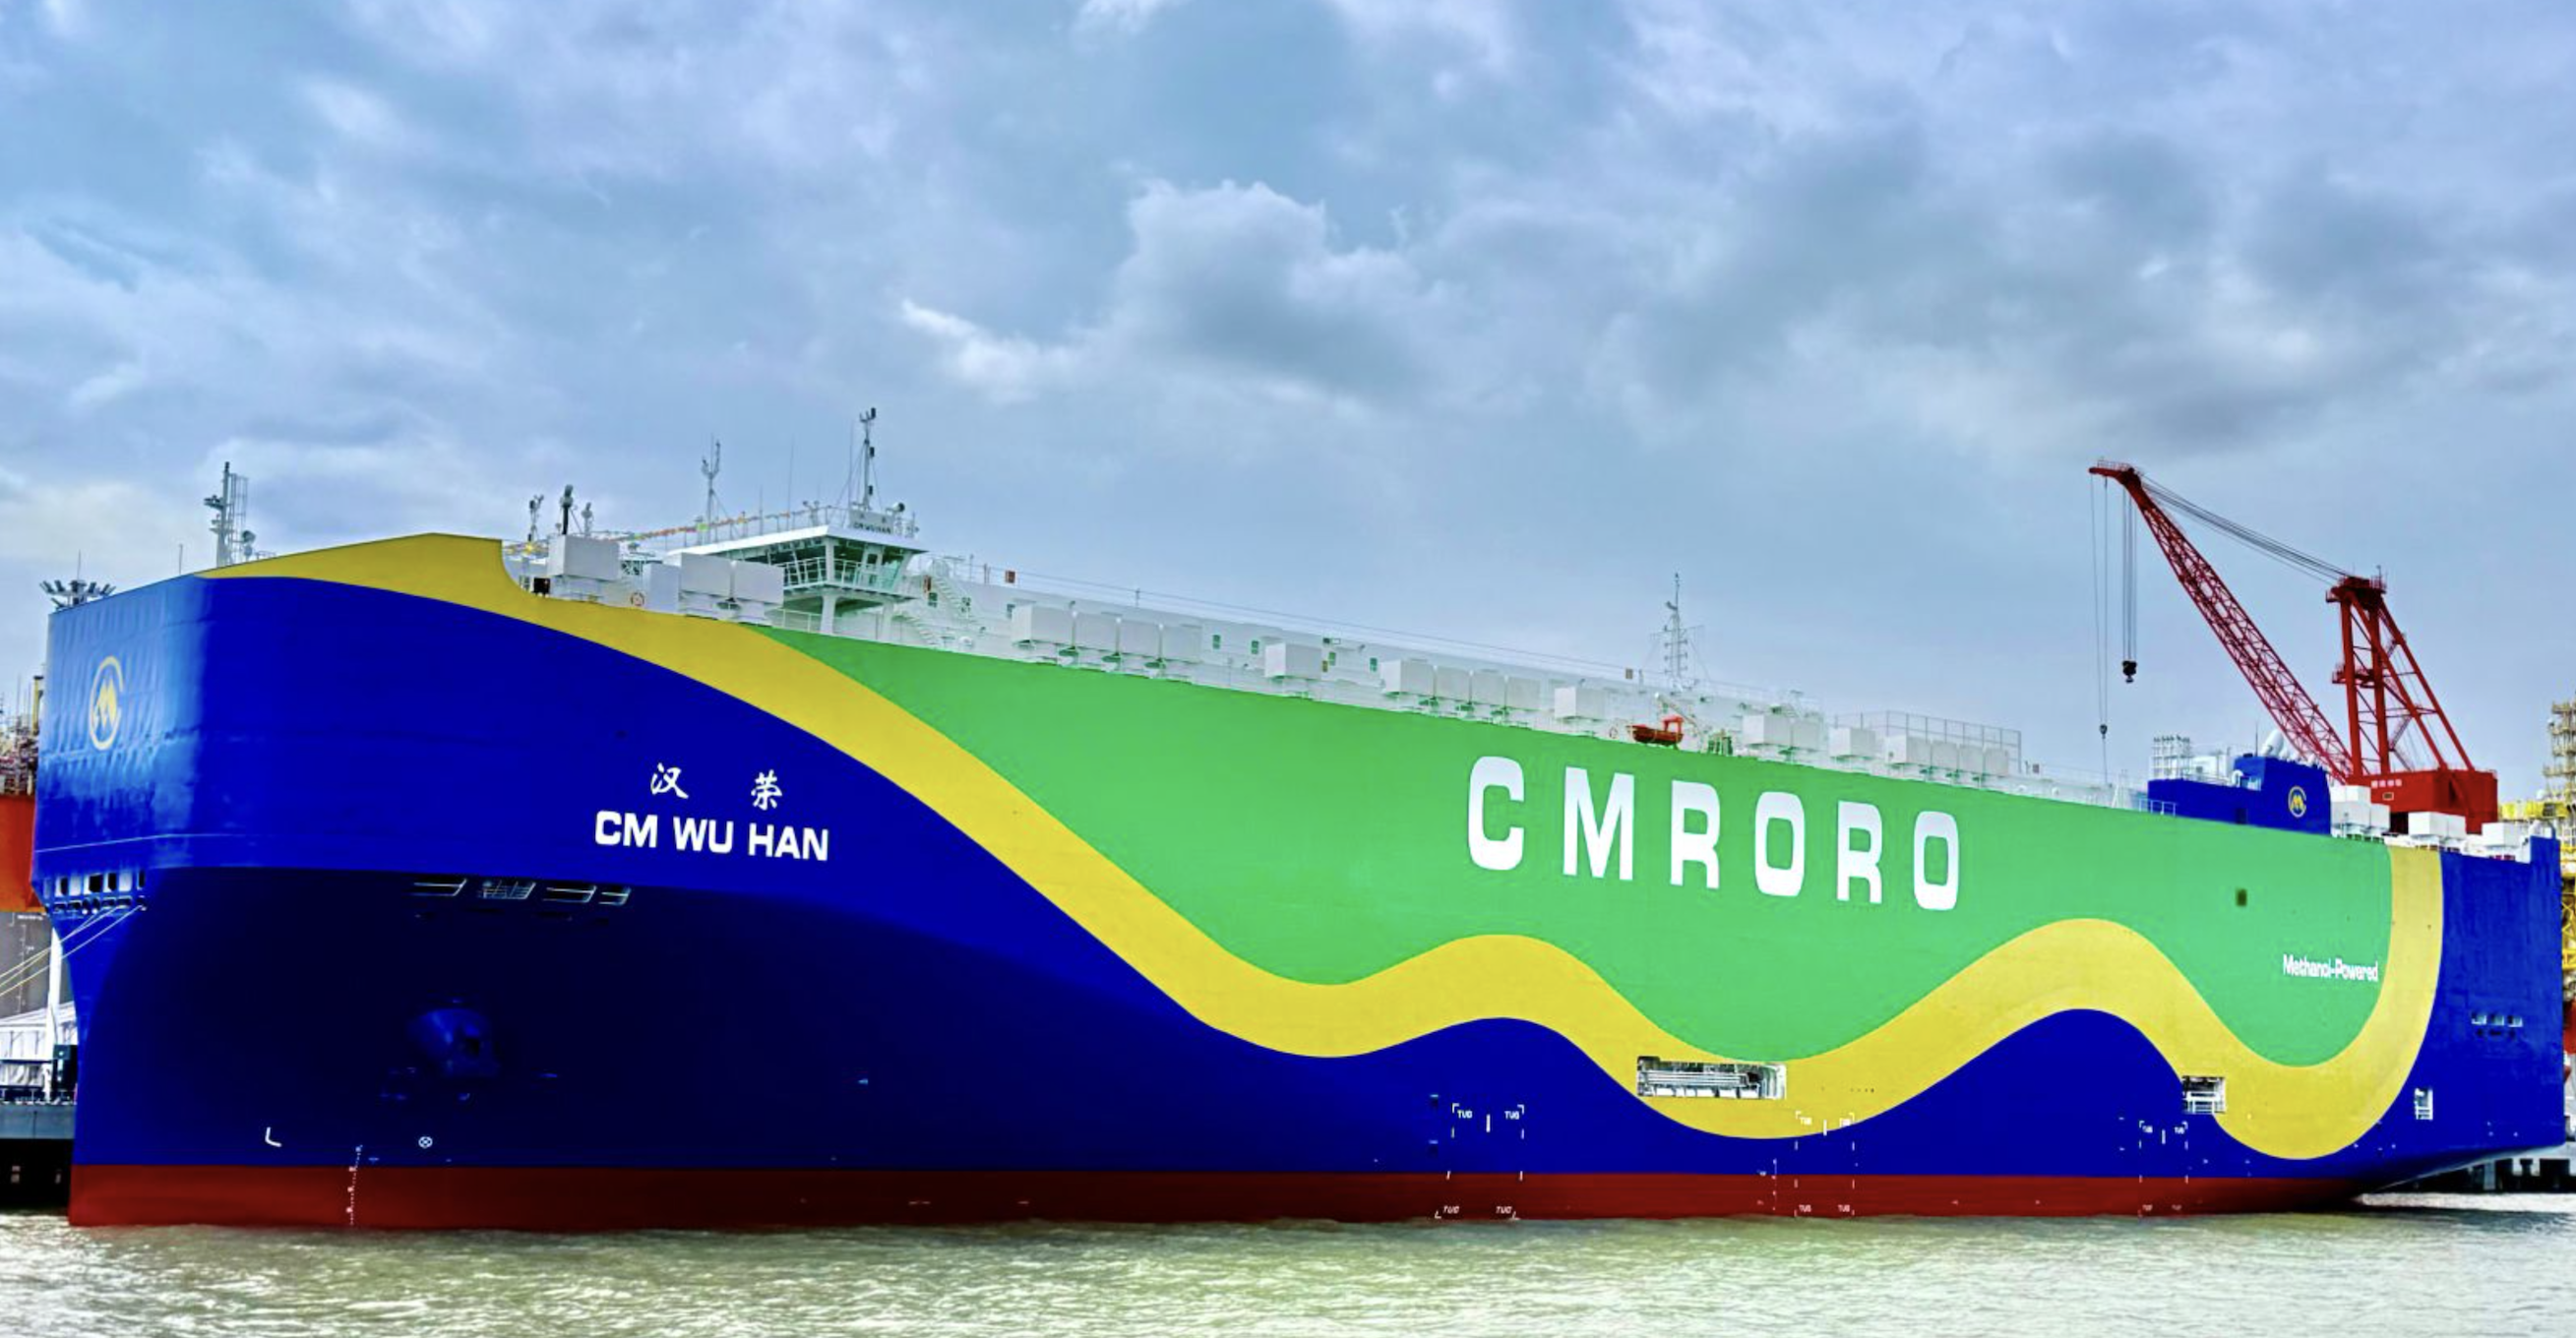
China Merchants Takes Delivery of Methanol Dual-Fuel Car Carrier CM WUHAN
 Car Carriers
Ningbo Ocean Shipping Plans Two More PCTCs to Expand Its Car Carrier Fleet
 Car Carriers
Another Chinese Shipowner Enters PCTC Market — and Another Chinese Yard Moves into 5,000-CEU Construction
 Car Carriers
BYD Has Bought another 10 More Ships, Says Stella Li,Executive Vice President of BYD
 Car Carriers
Up to 26 PCTC! Höegh Autoliners Signs 6 More Aurora Car Carriers with China Merchants
 Car Carriers
917 Chinese Vehicles Arrive at Chancay as COSCO SHIPPING Expands Rack-Based Auto Logistics
 Car Carriers
BYD Orders Another 10 x 9,200 CEU-CEU Car Carriers?
 Car Carriers
Up to 14 More PCTCs: Höegh Doubles Down on China as Aurora Programme Could Grow to 26 Ships
 Car Carriers
PCTC Are Running Short: COSCO Moves 13,052 Chery Vehicles to Europe in Containers, Tapping Boxship and Multipurpose Vessel Networks
 Car Carriers