A 15-Year-Old VLCC Sells for $161 Million as Tanker Asset Prices Surge
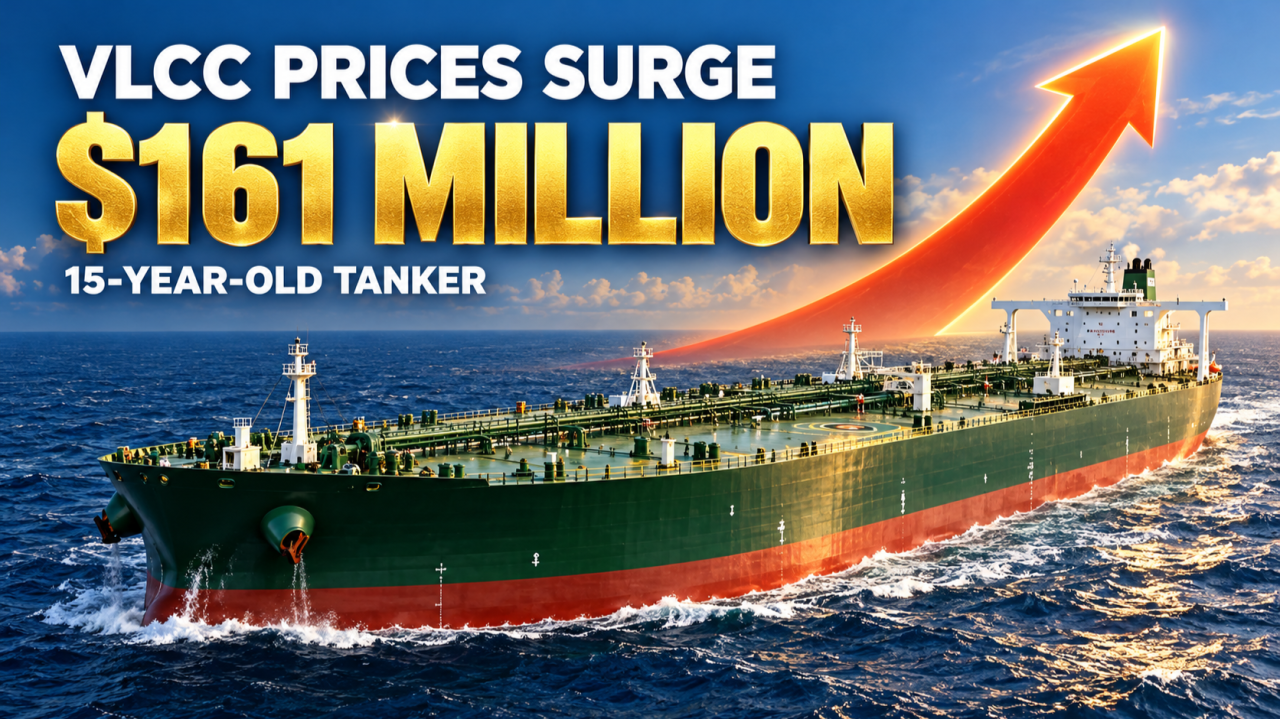
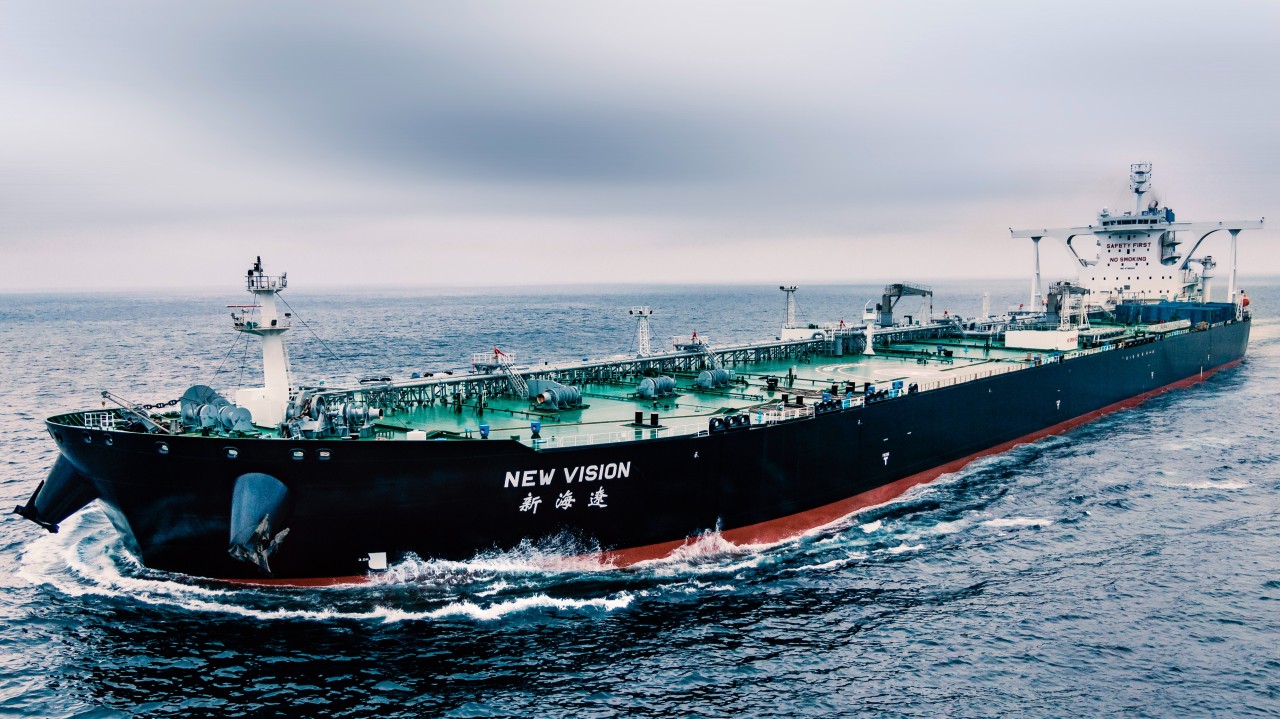
A 15-year-old very large crude carrier has been reported sold for $161 million, highlighting the sharp rise in the value of immediately available tanker capacity.
According to MB Broker’s sale-and-purchase report, the 320,105 dwt Eurospirit, built by South Korea’s Daewoo in 2011, was sold by Greek tanker owner Eurotankers, with ADNOC named as the buyer. The vessel is fitted with a scrubber and an eco main engine.

The transaction follows the reported $300 million en bloc sale of Olympic Target and Olympic Light, equivalent to an average of $150 million per vessel. Both tankers were also built in South Korea in 2011 and are fitted with scrubbers.
These transactions demonstrate the prices buyers are accepting for older VLCCs. Exceptional freight earnings, constrained vessel availability and long newbuilding lead times are driving a substantial premium for ships that can enter employment quickly. National oil companies and commodity traders are also placing greater value on controlling transport capacity.
Comparable Ships Change Hands at Exceptional Prices
The Olympic pair provides a useful comparison with Eurospirit. The 319,861 dwt Olympic Target was built by Hyundai Heavy Industries, while the 317,106 dwt Olympic Light was built by Hyundai Samho Heavy Industries. The sale report lists Onassis as the seller, with the buyer undisclosed.
Reported approximately a week earlier, the package transaction put the average price of the two ships at $150 million. Eurospirit’s $161 million sale price is $11 million, or approximately 7.3%, above that average. Equipment, maintenance condition, survey position, delivery arrangements and package terms affect individual prices, but the successive transactions place several comparable 2011-built Korean VLCCs in a significantly higher valuation range.

Other sales reinforce that picture. Maritime consultancy Frelsea’s Week 39 report recorded the sale of the Hyundai-built, 2011-delivered Atherina to South Korean shipowner Sinokor for $146 million. Greek shipbroker Carriers Chartering’s October 5 report listed the 314,000 dwt Sea Leopard, also built by Daewoo in 2011, at $169 million.
The appreciation extends to older vessels. Sinokor reportedly acquired the 2008-built Rain Cubic, formerly Shaybah, for approximately $59 million in February. A subsequent sale reported in September placed the price at around $90 million. The $31 million difference represents an increase of approximately 52.5% in the reported vessel price, before holding and transaction costs.
For owners that acquired ships earlier in the cycle, these movements create opportunities to realise substantial asset gains. For buyers entering at today’s prices, they establish a demanding capital commitment that must ultimately be supported by operating cash flow and the vessel’s remaining resale value.
Older Vessels Dominate an Active Sale-and-Purchase Market
Vessel valuation and analytics provider VesselsValue had recorded 14 VLCC transactions in September as of September 29, compared with five in August. Disclosed transaction value reached approximately $1.54 billion, around 4.8 times August’s $324 million. Some late-month transactions had yet to enter the register.
The age profile of the vessels changing hands is particularly revealing. Greek shipbroker Xclusiv reported that, as of September 14, 103 VLCC sales had been recorded during the year. These included 43 vessels aged 11–15 years, 32 aged 16–20 years and nine older than 20 years. Ships more than ten years old accounted for over four-fifths of the total, while only five were in the zero-to-five-year category.
Owners of modern VLCCs can continue earning substantial revenue in the prevailing market, giving them a strong incentive to retain their ships or demand a high sale price. Buyers seeking prompt delivery consequently have reason to consider well-maintained older vessels that meet the requirements of their intended trades and customers.
Older ships have also shown greater valuation sensitivity. Between July 10 and September 18, Xclusiv’s five-year-old VLCC assessment rose from $145 million to $172 million, an increase of approximately 18.6%. Its ten-year-old assessment increased from $115 million to $152 million, or about 32%, while the fifteen-year-old assessment climbed from $83.5 million to $135 million, nearly 61%.
A surge in near-term earnings can have a particularly large effect on an older vessel’s value. Its starting valuation is lower and its remaining operating life shorter, making the next few years of cash flow a larger component of its overall value. Buyers expecting to recover a substantial portion of their investment during the first several voyages may therefore accept prices that would be difficult to justify under more ordinary freight conditions.
Commercial suitability remains central to that calculation. Maintenance history, charterer acceptance and reliable performance determine whether an older ship can secure the employment needed to support its acquisition price.
Immediate Delivery Commands a Premium
Baltic Exchange asset assessments dated October 9 illustrate the importance of availability. The VLCC newbuilding reference stood at approximately $125.88 million, compared with $182.5 million for a five-year-old vessel and $156.62 million for a ten-year-old vessel.
On those benchmarks, the five-year-old ship was valued about 45% above the newbuilding reference, while the ten-year-old vessel carried a premium of approximately 24.4%.
The difference reflects when each asset can begin earning. An existing vessel can enter employment after delivery and any necessary inspections or repairs. A newly ordered ship must pass through procurement, construction and trials before generating revenue.
At exceptionally high freight levels, that waiting period becomes expensive. A future newbuilding may offer better fuel efficiency, lower maintenance requirements and a longer operating life, but its buyer must weigh those benefits against the earnings available before delivery. Current secondhand prices therefore incorporate the value of earlier access to the market.
High earnings also strengthen sellers’ negotiating positions. Continuing to operate a vessel produces cash flow, so an owner considering a sale must receive sufficient compensation for surrendering that opportunity. Rising freight expectations can lift both the price buyers are prepared to pay and the minimum amount sellers will accept.
Technical condition becomes especially important in this environment. Scrubber economics depend on fuel-price spreads and trading requirements, while consumption, speed and maintenance affect the revenue a ship retains. Additional time spent in a yard or awaiting repairs carries a larger opportunity cost when freight earnings are elevated.
Disruption Tightens Effective Vessel Availability
Disruption around the Strait of Hormuz has affected owners’ willingness to undertake particular voyages and added uncertainty to insurance, crew arrangements and loading schedules. This can create a significant gap between the number of VLCCs in the global fleet and the number available for a specific cargo within its loading window.
Ships may be committed to dedicated transport programmes, waiting for instructions, undertaking transfers or repositioning between regions. Some owners may reduce exposure to higher-risk trades. These circumstances constrain the pool of vessels competing for individual cargoes, strengthening the negotiating position of owners with suitable ships available.
Changes in crude sourcing can add further pressure. If Asian refiners increase purchases from the US Gulf or West Africa, longer voyages occupy tankers for more time. Each vessel completes fewer transport cycles, potentially increasing the number of ships required to move a similar volume of oil.
The Baltic Exchange’s Week 41 tanker report, published on October 9, assessed round-trip time-charter equivalent earnings on the Middle East Gulf–China TD3C route at approximately $1.41 million per day. West Africa–China TD15 was assessed at around $763,000 per day. The US Gulf–China TD22 route carried an assessed freight payment of approximately $79.61 million, corresponding to round-trip TCE earnings of about $637,675 per day.
These benchmark assessments deduct voyage expenses such as bunkers and port costs. Vessel operating expenses, financing and depreciation remain separate, while actual results depend on fixture timing, waiting time, vessel performance and contractual allocation of additional costs.
The exceptionally high assessments are nevertheless feeding directly into asset negotiations. Owners can compare an immediate sale with the potential earnings from retaining their vessels, while buyers assess how quickly available tonnage might recover part of its purchase price.
Energy Companies and Traders Invest in Transport Control
ADNOC Logistics & Services, the shipping and logistics business associated with Abu Dhabi National Oil Company, has been an important buyer of large crude and gas carriers.
On August 7, the company announced an investment of approximately $1.3 billion in six VLCCs and five very large gas carriers. The six VLCCs and three VLGCs were acquired through the secondhand market, with delivery scheduled for the third quarter. The remaining two VLGCs were newbuilding resales scheduled for fourth-quarter delivery. Completion of the programme was expected to increase its VLCC fleet to 14 vessels.
The company said the acquisitions would support ADNOC’s production, trading and export growth. For an energy group with recurring transport requirements, vessel ownership provides greater control over loading schedules and reduces dependence on securing ships at short notice.
The commercial value extends across the cargo business. Reliable transport helps fulfil sales contracts, maintain refinery supplies and capture trading opportunities between regions. Delays can affect inventories, customer commitments and the economics of the underlying commodity transaction. These considerations influence the value a cargo-owning buyer may assign to a vessel.
Commodity trader Trafigura is combining fleet ownership with external equity capital. Its majority-owned tanker company, Volare Shipping, began trading on Euronext Growth Oslo on October 5 after raising approximately $500 million through a private placement. Volare has six operating VLCCs and eight vessels under construction, with deliveries scheduled through 2028. Trafigura provides commercial management.
The structure brings vessel assets, financing and cargo-market expertise together. Outside investors contribute capital, while Trafigura retains a controlling interest and responsibility for commercial deployment.
New entrants are also appearing among independent owners. Abu Dhabi-listed maritime company Al Seer Marine announced the sale and delivery of the 2014-built Twin Pollux on September 9. Market reports identified the buyer as Chinese shipowner Zhejiang Changchang Shipping, with the vessel subsequently renamed CC Pacific. The transaction price was undisclosed.
Secondhand sales redistribute existing vessels rather than expand the physical fleet. Their effect on availability depends on how the ships are subsequently employed. Greater allocation to recurring cargo programmes or dedicated transport requirements can influence the capacity offered for individual spot-market cargoes.
Sellers Turn Strong Valuations into Realised Gains
High prices give existing owners an opportunity to crystallise asset appreciation and redirect capital. Sinokor’s reported transactions involving Rain Cubic and Atherina illustrate the scope to sell an older asset at an appreciated price while acquiring a younger vessel.
Belgian diversified shipping group CMB.TECH provides examples supported by corporate disclosure. Its second-quarter results, published on August 27, recorded approximately $98.2 million in gains from the sale of the 2012-built VLCCs Ilma and Ingrid. The sale of the 2016-built Donoussa was expected to generate a gain of approximately $74 million in the fourth quarter.
Such disposals release capital as the group develops a diversified fleet and invests in new vessels. Owners with ships acquired at lower prices can choose between retaining exposure to strong freight earnings and realising a substantial portion of the anticipated return through a sale.
Separate market reports have linked CMB.TECH to a potential resale of four VLCC newbuildings at approximately $250 million each, or $1 billion in total. The reported arrangement and pricing have not been confirmed in a company announcement.
Buyers and sellers can have sound reasons to act at the same point in the cycle. Their decisions depend on acquisition cost, available employment, capital requirements and willingness to retain exposure to future freight and asset-price movements.
Payback Depends Heavily on Early Earnings
The difference between short-term and longer-term charter references shows how strongly current valuations depend on the duration of elevated earnings.
Shipbroker AXIA’s Week 41 material placed a one-year VLCC charter reference at approximately $273,500 per day. The Baltic Exchange’s October 9 asset data showed a five-year charter reference of around $71,833 per day. Vessel specifications and charter terms affect these figures, but the substantial gap indicates a much higher value attached to capacity in the near term.
An illustrative cash-flow calculation demonstrates the sensitivity. For a vessel acquired at $161 million, assume 350 earning days per year and daily operating expenditure of approximately $7,800 incurred throughout the year.
At an average daily TCE of $200,000, annual cash generation after those operating expenses would be approximately $67.15 million. At $100,000 per day, it would fall to about $32.15 million; at $50,000, to around $14.65 million.
Those amounts are before financing, drydocking and other additional expenditure. On a simple, undiscounted basis, excluding resale proceeds, the corresponding recovery period for the acquisition price ranges from approximately 2.4 years at $200,000 per day to about 11 years at $50,000.
For a vessel already around fifteen years old, that difference is material. A longer recovery period brings greater exposure to maintenance requirements, future surveys and changes in customer acceptance as the ship ages.
Using the five-year charter reference of $71,833 per day as another illustrative earnings assumption produces approximately $22.3 million annually after the same operating-cost allowance, or around $111.5 million over five years. Subsequent employment and eventual resale value would need to cover the remaining acquisition cost, financing return and additional expenditure.
This makes the first period of ownership particularly important. Prompt delivery into well-paying employment can recover a meaningful share of the purchase price. A vessel requiring repairs, surveys or lengthy repositioning may miss part of that opportunity. Delivery timing and the first employment programme consequently carry unusual weight in current negotiations.
Future Deliveries Will Test Today’s Premiums
The delay between ordering and delivering ships supports the present premium for existing tonnage. Investment in new capacity is nevertheless increasing.
BIMCO reported in July that crude tanker contracting during the year had reached 234 vessels and approximately 60 million dwt, establishing a record annual contracting volume, with VLCC orders a major contributor.
Shipping analytics company Signal Group’s July report also pointed to rising crude tanker deliveries in 2027 and a more concentrated delivery peak towards the latter part of 2028. Today’s shortage of available vessels can therefore coexist with a substantial future expansion in supply.
The pace of older-vessel retirement will influence the eventual balance. Strong earnings encourage owners to fund repairs and surveys and retain ships that might otherwise move towards recycling. If those vessels remain commercially active as newbuildings arrive, net fleet growth could become more pronounced.
A reduction in transport disruption could also release effective capacity. Improved willingness to undertake particular voyages, shorter waiting periods and fewer repositioning constraints would allow ships to return to competition more quickly. Restored crude flows could simultaneously increase cargo demand, making the outcome dependent on the relative changes in volumes, voyage distances and vessel availability.
National oil companies, commodity traders and independent shipowners bring different cargo commitments, financing structures and commercial capabilities to their investment decisions. Their ability to capture earnings—and the wider value they assign to transport control—can produce different valuations for the same vessel.
The $300 million Olympic package and Eurospirit’s reported $161 million sale show how far buyers have raised their valuation of existing VLCC capacity. The returns on those investments will depend on how quickly the ships enter profitable employment and how much capital they recover before additional supply and changing trade conditions reshape the market.
READ MORE
 Tankers
An $81 Million Quote for One Voyage: How Long Can the Tanker Market Frenzy Last?
 Tankers
From Dubai Property to Tankers: TOP Ships Signs Four-Ship GSI Deal
 Tankers
Two Voyages Pay for a New VLCC?
 Tankers
VLCC Benchmark Tops $1 Million a Day: How Are Owners Using the Windfall?
 Tankers
4 Delivered, 4 More Ordered: Schoeller Returns to Chengxi for MR Tankers
 Tankers
Tianjin Southwest Maritime Chairman Liu Jichun Targets Asphalt Tanker Owner Xin Yuan
 Tankers
US Sanctions 17 Ships in Iran Crackdown, Naming China-Linked Owners
 Tankers
PIF Energy Plans $2 Billion VLCC Fleet for Gulf Crude Trade
 Tankers
TOP Ships’ Four-Tanker Deal Links Chinese Leasing With Long-Term Charters
 Tankers