Can Dry Bulk Match Tankers’ Earnings?

Exceptional tanker earnings have raised a question for dry bulk shipowners: could their market deliver a comparable surge in returns?
Signal Ocean’s market report published on 16 October put time-charter equivalent earnings on the Middle East Gulf–China VLCC route at approximately $1.36 million per day, based on its 15 October snapshot. Against that backdrop, the prospect of a similar earnings peak in dry bulk has an obvious appeal.
At the Ship Operations and Management Forum 2026, held in Shanghai on 19 October, Captain @chen changzheng , Commercial Director of Wah Kwong and Managing Director of Wah Kwong Bulk, approached the question through the sources of profitability and the long-term health of the industry.
“The profits we want are those earned through greater efficiency and by serving our customers,” he said, drawing applause from the audience.
Chen sees reasons for confidence in dry bulk’s long-term prospects, including underlying industrial demand, fleet renewal and the continuing transition towards more efficient shipping. He also believes that durable returns require a healthy relationship between shipowners, cargo interests and the wider supply chain.
His comments, considered alongside the forum’s other discussions and the analysis presented by Signal Ocean Senior Dry Bulk Market Analyst Esther Chua, suggest an industry with opportunities ahead. Capturing those opportunities will depend heavily on vessel selection, trading patterns and operating capability.

Long-term owners need a healthy market
Chen cautioned against assuming that the conditions behind exceptional tanker earnings would translate directly into dry bulk. The sectors differ in their cargoes, exposure to critical shipping routes and competitive structures. Developments in the Middle East also affect tanker and dry bulk trades to different degrees.
For dry bulk, the economics of the cargo deserve particular attention. Much of the industry transports basic raw materials, making freight a significant consideration in whether a shipment remains commercially viable.
Chen offered a hypothetical example: what would happen to raw material costs if daily bulk carrier hire reached $200,000 or $300,000? He warned that sharply higher transport costs could pass through industrial supply chains, contribute to inflation and affect living costs, particularly in poorer regions.
Shipowners need sufficient returns to maintain their vessels, service capital commitments and invest in replacement tonnage. Cargo producers and buyers also need commercially sustainable trading conditions. If transport costs remain beyond what an industry can absorb, the cargo base supporting shipping can come under pressure.
Chen’s concern also extends to the capital that exceptional earnings can attract. A rush of investors seeking short-term gains can stimulate asset transactions and fleet expansion. When conditions weaken, established operators remain exposed to the additional capacity and competition.
For a longstanding shipping business, the quality of a market therefore includes what happens after the peak. Chen’s preferred outcome is an industry in which owners earn reasonable returns through effective management and reliable service, while customers retain the ability to trade and invest.
Why Chen remains confident in dry bulk
Asked to describe the market, Chen favoured a phrase conveying confidence in the future. Shipping is a long-term business, he argued, and its prospects need to be assessed over a longer horizon than the immediate earnings cycle.
On demand, he discussed the relationship between the “world of bits” and the “world of atoms”. Artificial intelligence, digital technology and information services increasingly attract public and investor attention, but their development continues to depend on energy, raw materials and physical infrastructure.
Shipping connects those physical inputs with the industries and consumers that use them. In Chen’s view, growth in digital industries could create further demand for the resources and infrastructure that underpin them, offering opportunities for dry bulk transportation.
The commercial question is how that demand becomes actual cargo movements. Changes in production and consumption can alter origins, destinations, distances and vessel requirements. Owners need to understand those changes closely enough to position their fleets around them.
On supply, Chen highlighted the relationship between fleet ageing and replacement investment. Dry bulk renewal competes for shipbuilding resources with containerships, tankers and other vessel types, while deliveries take place over several years. The age and operating capability of the existing fleet therefore remain important alongside the orderbook.
He also expects environmental requirements to continue influencing competitiveness. As operating costs, technical standards and customer expectations evolve, the differences between efficient modern vessels and less competitive tonnage could become more pronounced.
Together, these factors underpin his confidence: dry bulk’s opportunities arise from continuing physical trade, fleet renewal and improvements in operating efficiency.
Higher freight must remain compatible with cargo economics
The perspective of a shipowner earning stronger freight can differ substantially from that of a mine, trader or refinery paying for transportation.
Xiaolei Liu, Big Data Director at Shanghai Metals Market (SMM), brought that distinction into the discussion. He said freight volatility had become a significant concern for some mining and refining businesses, prompting greater interest in tools that could help manage transport-price exposure.
Commodity prices, production costs and freight jointly determine whether a trade remains viable. Higher-cost producers with narrow margins are particularly sensitive to changes in logistics costs.
Bauxite provides an example. Liu explained that suppliers differ in both cost and product quality. When commodity prices and shipping costs change, buyers may concentrate purchases on origins offering a stronger overall economic proposition, increasing pressure on less competitive sources.
For shipping companies, a freight increase appears as stronger revenue. For mines and refiners, it can require a reassessment of procurement, sales and sourcing arrangements. Over time, those decisions can change the cargo flows on which vessel employment depends.
Resource-country policies introduce another variable. Liu pointed to the importance of monitoring Guinea’s mining policies and domestic alumina capacity development. If more ore undergoes processing before export, the volume and composition of seaborne cargo could change.
Chua’s presentation also highlighted the different vessel exposure of bauxite and alumina. Bauxite transportation is concentrated in Capesize vessels and very large ore carriers, while alumina predominantly uses smaller ships. Growth within the same industrial supply chain can therefore have different consequences across vessel classes.
These considerations reinforce Chen’s emphasis on a functioning customer relationship. Sustainable shipping revenue depends on cargo interests continuing to produce, purchase and move goods.
Distance and turnaround matter alongside tonnes
Changes in trade geography can support dry bulk demand even when cargo volumes grow relatively modestly.
Chua stressed that headline tonnage rarely tells the complete shipping story. The same quantity of cargo can require more vessel time if it travels farther or takes longer to complete its transportation cycle. Assessing demand requires attention to the cargo, the journey and the vessels available to carry it.
Her China-bound iron ore fines sample illustrated the point. Based on the 14 October snapshot, cargo tonnes recorded for January–August 2026 increased by approximately 2.9% year on year, while recorded tonne-miles rose by about 5.3%. The sample excluded very large ore carriers.
The comparison shows how sourcing and distance can add to transport work beyond the increase in cargo tonnes alone. Sustained longer-haul programmes can support vessel employment, provided the underlying trade remains commercially viable.
Tianxiang Li, Greater China President at Lloyd’s Register, also urged a balanced assessment of geopolitical disruption. Waiting, delays and longer transportation distances can absorb capacity. At the same time, higher energy and transport costs, together with interruptions to trade, can suppress demand.
Regional conditions add further complexity. Chua’s selected Panamax loading observations showed growth in the US Gulf alongside weaker performance in the east coast of South America and parts of Europe. Even where cargo volumes increase, the freight response depends on timing: when cargo becomes ready, which ships are suitable and whether those ships can arrive within the required loading window.
For operators, matching cargo readiness, vessel position and laycan can make a material difference to earnings. Annual market growth alone does not establish the quality of an individual trading opportunity.
The 2027 challenge: absorbing additional capacity
Confidence in dry bulk’s long-term role can coexist with near-term pressure in particular vessel classes. Chua’s 2027 scenario analysis showed how uneven that pressure could be.
Her model compared growth in transport workload, measured in required vessel-days, with growth in nominal fleet capacity measured in calendar days. It covered dry bulk and multipurpose vessels, including coastal movements, and used estimated 2026 activity as the comparison base.
For Panamax, modelled required vessel-days increased by approximately 0.2%, against growth of about 4.9% in fleet calendar-day capacity. The corresponding figures for Supramax were around 1.1% and 4.8%. These classes showed the largest gaps between workload growth and nominal capacity growth.
For Capesize vessels, including very large ore carriers, modelled workload increased by approximately 1.8%, compared with fleet capacity growth of about 3.3%. Handysize was close to balance, with respective increases of approximately 1.2% and 1.1%.
The analysis describes conditional pressure to absorb additional capacity. Cargo assumptions, route allocation and operating conditions affect the results, while actual deliveries, vessel removals and turnaround times can alter market outcomes. The figures do not directly establish future freight rates or company profitability.
The cargo scenario was also selective. Within the export categories presented, additions were concentrated in iron ore and combined bauxite and alumina, while thermal coal declined. Different commodities create different voyages and draw on different vessel classes.
This gives practical substance to Chen’s emphasis on respecting supply and demand. Opportunities need to be assessed at the level of vessel type, route, customer and delivery timing. Securing capacity is only part of the task; deploying it into business that can generate an adequate return is equally important.
Wah Kwong combines ownership with operating capability
Chen’s comments on corporate strategy offered an explanation of how Wah Kwong intends to build that capability.
A strategy should begin with what the organisation can execute, he said. Its team and operating structure must support the proposed business. The next consideration is customer value: what does the customer need, and which capabilities must the company develop to meet that need?
Cooperation with other shipping companies, leasing institutions and management partners can broaden the business network and strengthen resilience. Asset ownership and capital intensity then become tools for implementing the strategy, selected according to the requirements of the business.
Wah Kwong’s recent developments provide a practical example. On 15 April, the group announced the establishment of Wah Kwong Bulk as a shipowning dry bulk operator focused on the midsize market.
As Xinde Marine News previously reported, the company disclosed at the time that it operated 30 bulk carriers, with Ultramax and Kamsarmax as core vessel types serving cargoes including grain, ore and bauxite. It outlined a target of expanding to 50–60 vessels by 2030, including 30 owned ships. Chen also explained that the business would combine owned and operated tonnage.
Wah Kwong’s website describes a fleet platform built around vessels owned or controlled by the parent group, supplemented by long-term or bareboat charters from third-party owners. Its services include freight transportation, chartering and post-fixture management.
The approach brings assets, cargo relationships and market execution closer together. Owned and controlled tonnage provides a foundation for customer service, while chartered vessels and flexible commercial arrangements help match specific transportation requirements.
Market levels will continue to affect earnings. Voyage planning, fleet positioning, cost control and customer relationships also influence how much value an operator can retain from those conditions. These are capabilities that a company can develop over time, consistent with Chen’s preference for profits earned through efficiency and service.
Building profitability through the cycle
Other participants similarly emphasised the need to combine commercial opportunity with preparation for changing conditions.
Niwei Xu, Executive Vice President of Guohang Ocean, described adjustments to the company’s domestic and international deployment, supported by vessel renewal and changes in operating arrangements. Entering a different market requires investment and compliance with its technical and operational requirements. Future expansion, he argued, must respond to supply and demand.
Xu Tao, General Manager of Shandong Shipping, expressed a related principle: companies welcome a strong market, but their businesses cannot depend on strong conditions continuing indefinitely. Geopolitical changes and reduced transport efficiency can support vessel demand while simultaneously increasing the difficulty of safe operations and supply-chain management.
Lloyd’s Register’s Li also placed investment within the vessel’s full operating life. A ship ordered today may remain in service for twenty years or longer. Its competitiveness will depend on conditions at delivery and on subsequent developments in fuels, efficiency and technical requirements. Short-term earnings provide an incomplete basis for such a commitment.
Dry bulk may yet experience another period of exceptional returns. The discussions in Shanghai identified both enduring demand foundations and meaningful differences between vessel classes. Whether these produce tanker-like extremes will depend on the particular balance of cargo, capacity and trading conditions.
Chen’s emphasis remains on what a company can build within that uncertain environment. For long-term owners and operators, reliable customer relationships, efficient ships and disciplined execution provide a basis for earning returns as market conditions change. Those capabilities will remain commercially valuable well beyond the next freight-rate peak.

READ MORE
 Dry Cargo
How Much Longer Can Dry Bulk Stay Strong?
 Dry Cargo
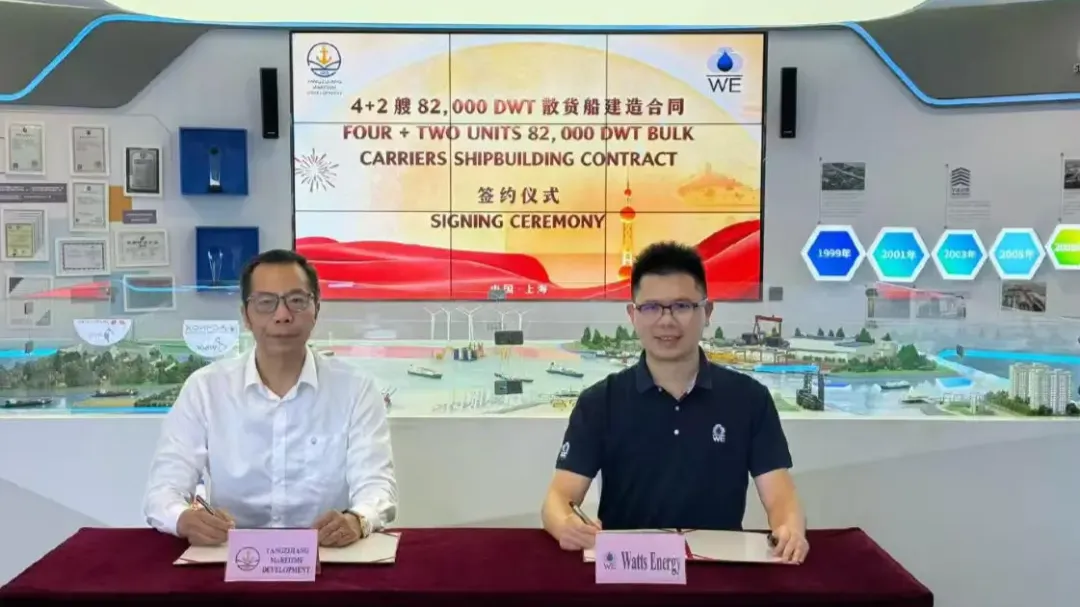
Yangzijiang Maritime Orders 4+2 Kamsarmaxes as Watts Energy Expands into Merchant Shipbuilding
 Dry Cargo
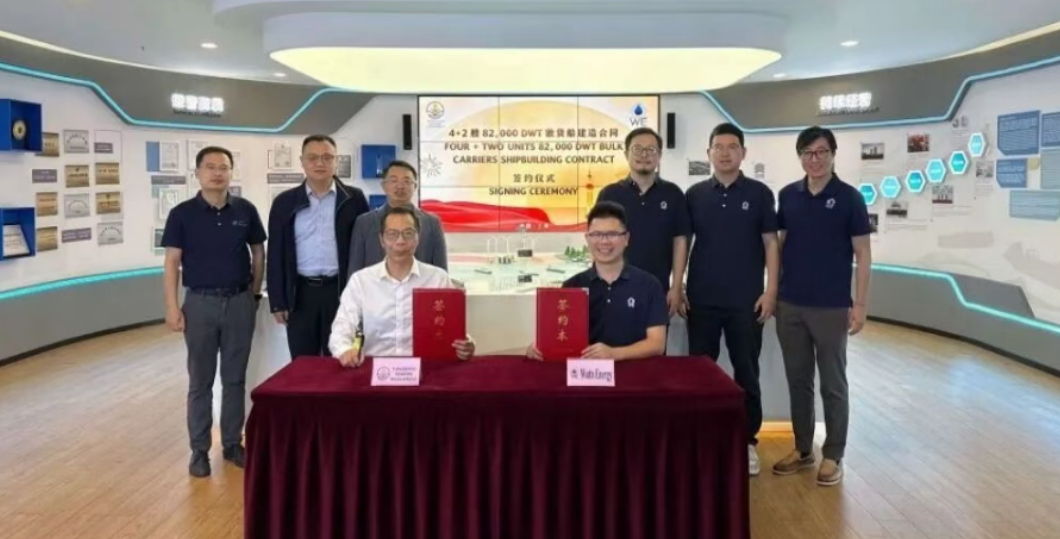
Yangzijiang Maritime linked to 4+2 Kamsarmax order
 Dry Cargo
Paliou Urges Fleet Discipline as Dry Bulk Faces Rising Supply and Changing Demand
 Dry Cargo
Black Sea Wheat Loadings Plunge 78% as Grain Trade Reroutes
 Dry Cargo
China Merchants Signs $2.8 Billion-Plus Simandou Shipping Deal
 Dry Cargo
Seaspan Enters Newcastlemax Market, with Yangzijiang Set to Build Two Tri-Fuel Ore Carriers
 Dry Cargo
Shipowners Bet on Ultramaxes: 42 Ships for Chinese Yards, Deliveries Stretch into 203
 Dry Cargo
“We Are Buying Ships”: Why Dry Bulk Is Beating Expectations
 Dry Cargo